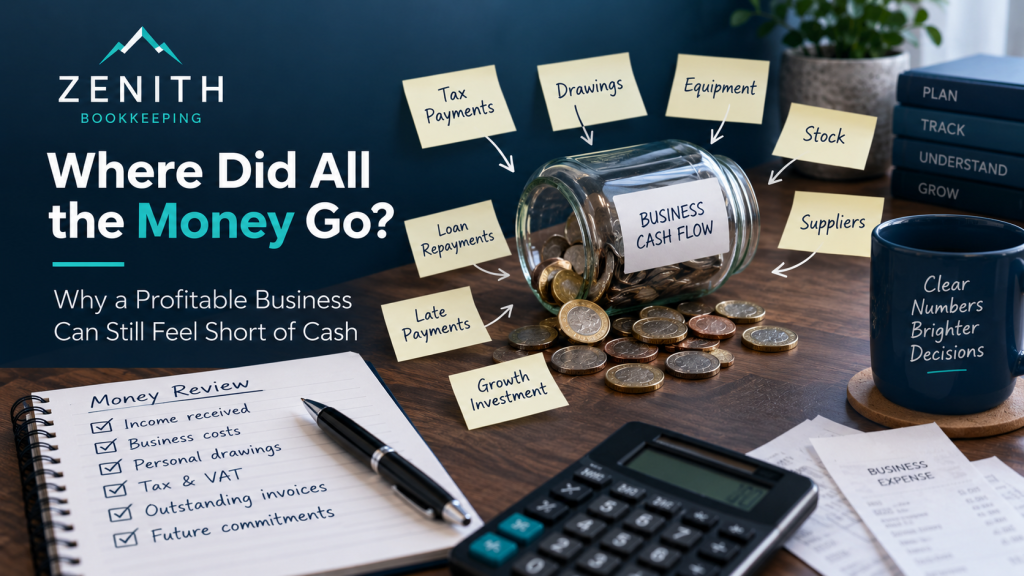
Why a Profitable Business Can Still Feel Short of Cash
You have had a good year. You can feel it because your Sales are up. Customers have been buying, and your bookkeeping records suggest the business has made a profit.
So you look at the bank account nd wonder:
Where is it?
Where did all that money go? It is one of the most frustrating questions a sole trader can ask.
You know you have been busy. You remember the invoices going out. You can see the turnover. You may even know the business is profitable. And yet there never seems to be as much money sitting in the account as you expected.
That does not necessarily mean something is wrong. But it does mean there is something worth understanding.
Throughout this series, we have looked at late payments, tax reserves, bank balances, break-even, quiet months and customer profitability.
This article brings many of those ideas together.
Because profit and cash are connected, but they are not the same thing.
Understanding where the difference comes from can remove a great deal of frustration from running a business.
Profit does not mean there should be a pile of cash somewhere
This is probably the most important point.
If your records show a £30,000 profit, it does not mean there should be £30,000 sitting untouched in your bank account.
Profit is a measure of financial performance over a period.
Cash is what is moving into and out of your bank account.
Those two things do not always happen at the same time. And they are affected by different things. You may have generated profit while also:
- Taking money out personally.
- Paying tax.
- Buying equipment.
- Repaying borrowing.
- Building stock.
- Waiting for customers to pay.
- Paying bills relating to an earlier period.
- Investing money back into the business.
The profit has not necessarily disappeared.
It has been used.
The important question is:
Used for what?
Start with the obvious place: you
For a sole trader, one of the largest destinations for business cash is often the owner.
That is entirely normal.
The business exists, at least in part, to provide you with an income. But personal drawings can easily become disconnected from profitability. Imagine the business makes £35,000 profit during the year. During that same period, you withdraw £2,500 every month for personal spending.
That is £30,000 taken from the business.
Add tax payments, equipment purchases and other cash commitments, and it becomes much easier to understand why the bank account does not contain £35,000 at the end of the year.
The key is not to stop taking money out. It is to understand how much the business can sustainably provide.
Drawings can creep upwards
Personal withdrawals do not always increase because somebody consciously decides to give themselves a large pay rise. Often they creep.
An extra £200 this month. Another £300 because of a household bill. A larger withdrawal after a particularly good customer payment. Over time, the amount taken from the business exceeds expectations.
Because the withdrawals appear as individual bank transactions, it is easy to miss the annual total.
Try adding up everything you have taken personally over the last 12 months.
The number may surprise you. That is not necessarily bad news. It simply gives you a clearer picture of where some of the cash has gone.
Tax may have taken a larger share than you remember
Tax payments can also distort how a year feels financially.
You earn money throughout one period but may pay tax later.
When the tax payment eventually leaves the bank account, it can feel as though current cash has suddenly disappeared.
That is one reason we previously discussed The Tax Pot Habit.
When tax money is separated gradually, the final payment feels less like a sudden reduction in business cash.
Without that separation, a £5,000 or £10,000 tax payment can make a healthy bank balance look very different overnight.
The money has not been mysteriously lost. It has met a financial commitment that arose from earlier profits.
Customers may owe you part of your profit
Here is another important difference between profit and cash.
You can have made a sale without having received the money.
Suppose you complete £8,000 of work during September and invoice your customers.
Those sales may form part of the business’s financial performance.
But if the customers do not pay until October or November, the cash will not be available to you yet.
On paper, the business has generated income.
In the bank, you are still waiting.
This is why we spent time earlier in the series looking at late payment.
A profitable business can still experience cash-flow pressure if customers consistently take too long to pay.
Look at what customers owe you
If you are wondering where the money has gone, an aged customer report can be revealing.
Perhaps the money has not gone anywhere.
Perhaps it has not arrived yet.
You might discover:
- £1,500 due next week.
- £2,000 already overdue.
- £800 promised for Friday.
- £3,000 invoiced but not due for another three weeks.
That is £7,300 connected with work already completed but not yet sitting in your account.
Suddenly the financial picture looks different.
This is why sales are not the same as cash received.
Some of the money may be sitting on a shelf
For businesses carrying stock or materials, cash can also become tied up.
Imagine you spend £5,000 building up stock. The cash has left the bank. But you have not necessarily lost £5,000. You have exchanged cash for assets the business intends to sell or use.
The same can happen with:
- Materials.
- Spare parts.
- Packaging.
- Work in progress.
- Items purchased ahead of future jobs.
Too much stock can certainly become a problem. But it helps to understand the distinction. The money may not have disappeared. It may have changed form.
Equipment can make cash disappear quickly
A profitable year is often when business owners decide to invest.
A new laptop.
Tools.
Machinery.
Office furniture.
A vehicle deposit.
Specialist equipment.
Imagine you spend £6,000 on equipment.
Your bank account is immediately £6,000 lower.
But depending on the nature of the purchase and the accounting treatment, the effect on reported profit may not simply mirror the cash payment at that exact moment.
For management purposes, the important point is simpler:
You have turned cash into something the business now owns or uses.
Again, the money has not simply vanished.
It has been invested.
The question is whether that investment was deliberate and worthwhile.
Debt repayments can confuse the picture
Suppose you borrowed £15,000 to buy equipment. When the loan was originally credited to the bank account, that £15,000 was not profit from trading. It was borrowed money.
As you repay it, cash leaves the business. But repaying the amount borrowed is not the same thing as paying a normal trading expense.
This is another example of why simply comparing profit with the bank balance can be misleading.
The bank account records cash movements.
Profit measures something different.
Both matter.
But they answer different questions.
VAT can make the account look healthier than it really is
For a VAT-registered business, money collected from customers can temporarily increase the bank balance.
But part of that money may later need to be paid to HMRC. Imagine a customer pays you £6,000, including £1,000 VAT. Your bank balance rises by £6,000.
That does not mean the entire £6,000 is effectively available as business income.
Once eligible VAT on purchases and other relevant adjustments are taken into account, some of the amount collected may ultimately be due to HMRC.
This is another reason a large bank balance can create a false sense of security.
Some of the money has already been allocated to another destination.
Annual bills can create uneven months
Some business costs arrive monthly.
Others do not.
Perhaps once or twice a year you pay:
- Insurance.
- Professional subscriptions.
- Software renewals.
- Vehicle costs.
- Equipment servicing.
- Membership fees.
- Website costs.
A business may therefore appear to generate plenty of surplus cash during several months and then experience a significant drop when a cluster of annual bills arrives.
Nothing unusual has necessarily happened.
The timing of the payments is simply uneven.
One way to reduce the surprise is to spread the cost mentally, or financially, across the year.
If an annual bill is £1,200, think of it as £100 a month.
You might even reserve that £100 monthly.
The eventual £1,200 payment has already been prepared.
Small spending deserves attention too
Not every cash leak comes from a major purchase. Sometimes money leaves the business through dozens of small decisions.
Subscriptions.
Apps.
Software.
Bank charges.
Coffee meetings.
Parking.
Delivery fees.
Small online purchases.
Advertising experiments.
Unused memberships.
None of them appears particularly important. But imagine you identify £250 a month of spending that no longer provides much value.
That is £3,000 a year.
Small expenses deserve proportionate attention, not obsession. The aim is not to question every £5 purchase. It is to make sure recurring spending still earns its place.
Growth can consume cash
This can catch successful businesses by surprise. Growth sounds as though it should immediately produce more money. Sometimes it does the opposite first. You win more work. So you need to:
- Buy more materials.
- Carry additional stock.
- Use more subcontractors.
- Hire somebody.
- Increase marketing.
- Purchase equipment.
- Take larger premises.
- Spend more before customers pay.
The business can become more profitable while simultaneously becoming more cash-hungry. This is one reason growing businesses sometimes experience cash-flow difficulties. The problem is not necessarily lack of sales. The business may simply be funding its growth.
Faster growth can require more working capital
Imagine each new job costs you £2,000 to deliver before the customer pays.
Previously, you handled two jobs at a time.
You needed roughly £4,000 available to fund them.
Now demand increases, and you handle six simultaneously.
You may need £12,000 before the associated customer payments arrive.
The business has grown.
The order book looks excellent.
But your cash requirement has tripled.
That is why growth should be planned financially as well as commercially.
More sales do not automatically produce more immediate cash.
Discounts may be eating more than you think
We touched on this in our previous article on customer profitability. Suppose you are turning over more than ever. But you have achieved that growth partly through:
- Discounts.
- Special deals.
- Lower prices for large customers.
- Free additional work.
- Increased delivery costs.
Turnover rises.
Margin does not rise at the same rate.
You become busier.
The bank balance does not improve as expected.
This is where focusing only on sales can become misleading.
The question is not:
“How much are we selling?”
It is:
“How much is left after generating those sales?”
The business may simply not be making enough profit
This possibility should not be ignored.
Sometimes the answer to “Where did all the money go?” is not complicated.
The business may be generating less profit than the owner believes.
Perhaps:
- Prices are too low.
- Costs have increased.
- Too much time goes uncharged.
- Discounts have grown.
- Low-margin work dominates.
- Overheads have crept upwards.
- Personal drawings are too high relative to earnings.
This is why current bookkeeping matters. Without reliable numbers, it is easy to judge success by busyness. But as we have already seen in this series:
Busy does not always mean profitable.
Separate four different questions
One of the easiest ways to create clarity is to stop asking one vague question:
“How are we doing?”
Instead, ask four.
1. Are we profitable?
Is the business generating more income than the relevant costs of operating it?
2. Do we have enough cash?
Can we meet the commitments falling due?
3. Are customers paying us quickly enough?
How much money is tied up in unpaid invoices?
4. Are we taking too much out?
Are personal drawings leaving enough money for tax, reserves and future business needs?
A business can answer:
- Yes to profitability.
- No to cash.
- No to customer payment speed.
- Yes to excessive drawings.
That gives you something useful to work on.
“How are we doing?” does not.
Follow the money
If you genuinely want to understand where the money went, start with the bank account — but do not stop there.
Look at the last 12 months and group the major cash movements.
For example:
Money in
- Customer payments.
- Other business income.
- Loans or finance introduced.
- Personal money introduced into the business.
Money out
- Direct business costs.
- Overheads.
- Tax.
- VAT.
- Personal drawings.
- Loan repayments.
- Equipment.
- Stock.
- Other investments.
- One-off costs.
You are not trying to rebuild a complete set of accounts yourself. Your bookkeeping should already be doing much of that work. You are trying to understand the story.
Create a simple Cash Story
Take a hypothetical business.
During the year:
Cash received from customers: £90,000
Then consider:
- £30,000 business running costs.
- £24,000 personal drawings.
- £8,000 tax payments.
- £5,000 equipment purchases.
- £4,000 loan repayments.
- £3,000 increase in stock.
That accounts for £74,000 of cash.
There may also be timing differences, VAT and other movements.
But the mystery is already disappearing.
You can see where the cash has been used.
This is far more helpful than looking at the year-end bank balance and concluding:
“I earned £90,000. Where has it all gone?”
You did not personally earn £90,000.
The business received £90,000 and used it for several purposes.
Give surplus cash a job before it disappears
One lesson that has run throughout this series is that unallocated money is easy to spend.
So when the business has a good month, decide what the surplus is for.
Perhaps divide it between:
- Tax.
- VAT.
- Business reserve.
- Planned investment.
- Personal drawings.
- Debt reduction.
This does not need to become complicated.
The purpose is intention.
If every pound remains in one current account, it all looks available.
Give it a job and the picture becomes clearer.
Compare profit with personal drawings
This is a particularly useful annual exercise for sole traders.
Ask:
What profit has the business generated?
Then:
How much have I taken personally?
Then:
How much tax has been or will need to be paid?
If drawings plus tax continually consume almost all available profit, it becomes easier to understand why the business never builds reserves.
That may be perfectly acceptable if it is a deliberate choice.
But if your goal is to create a stronger business, some profit eventually needs to remain within it.
That retained financial strength can help fund:
- Quiet months.
- Growth.
- Equipment.
- Opportunities.
- Unexpected costs.
Check whether your lifestyle has grown with turnover
This can happen gradually.
The business improves.
Personal drawings increase.
Household commitments increase too.
Then the business needs to perform at the new level simply to maintain everything.
A temporary slowdown suddenly feels much more serious.
There is nothing wrong with benefiting personally from building a successful business.
That is one of the reasons you work so hard.
But it helps to know your minimum personal requirement separately from your preferred lifestyle spending.
That gives you more flexibility if trading conditions change.
Use percentages carefully
Some owners like to divide receipts automatically.
For example:
- A percentage to tax.
- A percentage to reserves.
- A percentage available for drawings.
This can be an excellent discipline.
But avoid assuming somebody else’s percentages will automatically work for you.
Different businesses have different:
- Margins.
- Tax positions.
- Overheads.
- VAT obligations.
- Personal requirements.
- Growth plans.
Use your own figures.
Good systems should reflect your business, not somebody else’s Instagram post.
Look backwards — and forwards
Traditional bookkeeping is often thought of as historical.
What happened last month?
What did we spend?
What did we earn?
That information matters.
But combine it with one forward-looking question:
What does the money need to do next?
Over the next eight to twelve weeks:
- Which bills are coming?
- What tax is approaching?
- What customer payments are expected?
- What investment is planned?
- Are there quieter periods ahead?
- Will personal drawings change?
Now your bookkeeping begins to help you manage the future rather than simply explain the past.
A useful monthly Money Review
Set aside perhaps 30 minutes once a month.
Ask these seven questions.
1. What did we earn?
Look at income and profitability, not just bank deposits.
2. What did we spend?
Check for unusual or increasing costs.
3. What did I take personally?
Know your drawings.
4. What do customers still owe us?
Review outstanding invoices.
5. What money is already committed?
Tax, VAT, suppliers and upcoming costs.
6. What genuinely remains available?
Do not confuse the total bank balance with free cash.
7. What needs attention next month?
One action may be enough.
Perhaps:
- Chase invoices.
- Reduce a subscription.
- Increase the tax transfer.
- Review a price.
- Build the reserve.
- Postpone a purchase.
Small adjustments made regularly can prevent much larger problems later.
The five-minute “Where Did It Go?” check
If you do nothing else after reading this article, try this.
Write down these five figures for the last 12 months:
1. Total customer income received
2. Total business costs paid
3. Total personal drawings
4. Tax and VAT paid
5. Major equipment, debt or investment payments
You may not have every figure immediately.
That is okay.
Your bookkeeper can help.
The exercise itself reveals what information you currently understand and what remains unclear.
Then ask:
Does the movement in my bank balance now make more sense?
In many cases, it will.
Where good bookkeeping fits in
Good bookkeeping should help answer the question:
“Where did the money go?”
Without reliable records, you are left with:
- Bank statements.
- Memory.
- Assumptions.
- A vague feeling that the business should have more cash.
With current records, you can see:
- What customers paid.
- What remains unpaid.
- What the business spent.
- Where costs are rising.
- What you withdrew personally.
- How the business is performing.
- What information needs to be passed to your accountant or tax adviser?
At Zenith Bookkeeping, we believe this is where bookkeeping becomes genuinely useful.
Keeping accurate records is important.
Understanding what those records are telling you is better.
Because clarity gives you choices.
A final thought: the money usually hasn’t vanished
When a profitable business feels permanently short of cash, it is tempting to believe something does not add up.
Sometimes something genuinely does need attention.
But often the money has not vanished.
It has gone somewhere identifiable.
To you.
To HMRC.
To suppliers.
Into equipment.
Into stock.
Into repaying finance.
Into growth.
Or perhaps it is still sitting in your customers’ bank accounts waiting to be paid.
The objective is not to keep every pound sitting untouched.
Businesses exist to use money.
The goal is to understand where it is going and whether those choices are strengthening or weakening the business.
That is what financial control really means.
Not having the largest possible bank balance.
Not cutting every expense.
Not obsessing over every transaction.
But knowing enough about the numbers to make deliberate decisions.
And when you have that clarity, the question changes.
Instead of:
“Where did all the money go?”
you can say:
“I know where the money went — and I know what we need to do next.”
Would you like a clearer picture of where your business money is going?
If you are a sole trader or small-business owner in Norfolk and your business seems busy and profitable, but the cash position never feels as comfortable as expected, Zenith Bookkeeping can help.
Clear, current bookkeeping can help you understand what is coming in, where money is being spent, what customers still owe and how the financial pieces fit together.
Zenith Bookkeeping provides straightforward bookkeeping support and practical financial organisation in plain English.
Because the numbers should not leave you with more questions.
They should help you make better decisions.
Start a conversation with Zenith Bookkeeping today and build a clearer picture of where your money is going — and where you want your business to go next.
This article provides general information and should not be treated as individual accounting, tax or financial advice. The treatment of income, expenditure, assets, drawings and tax depends on individual circumstances and the accounting basis used. Obtain appropriately qualified advice where necessary.