Why a Cash Buffer Can Give You More Than Financial Security
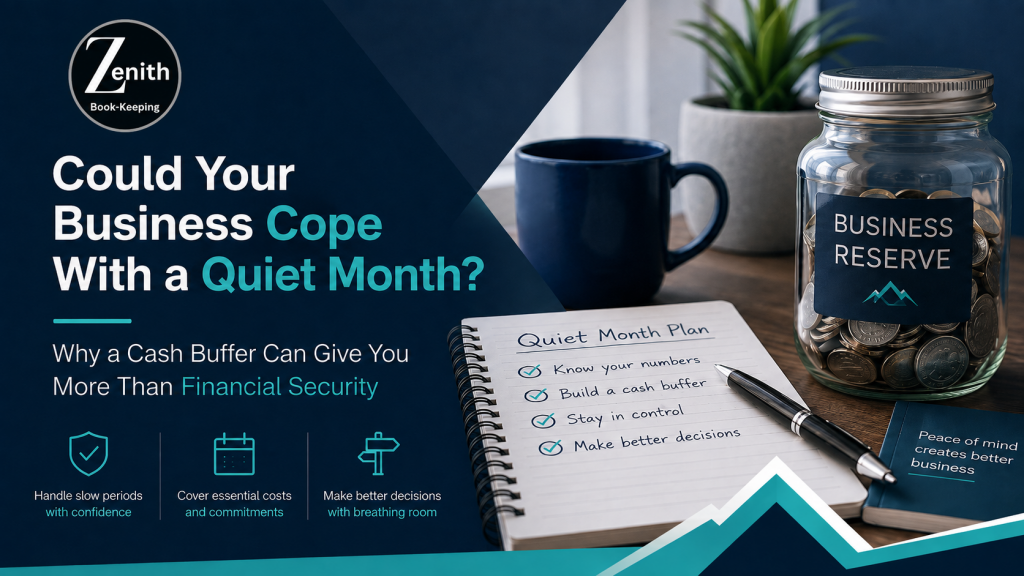
Let’s face it, some months are simply better than others for a variety of reasons, and when this is the case, you can often get a false sense of security, but as we know, all that glisters is not gold.
You may have a run of new customers, several invoices land at once, and the bank balance starts to look reassuring. Then the following month feels completely different.
- A customer delays a project.
- Another pays later than expected.
- A few enquiries disappear.
- You take a week off.
Or perhaps nothing dramatic happens at all — business is simply quieter.
For most sole traders and small businesses, fluctuations are normal.
The important question is not:
“Will I ever have a quiet month?”
It is:
“What happens to the business when I do?”
In our recent article, “How Much Does Your Business Need to Earn Before You Make a Penny?”, we examined the importance of understanding the income threshold before a business starts generating profit.
This article takes that one step further.
Because even if your business is profitable overall, there may still be individual weeks or months when income falls below normal.
The businesses that cope best are not necessarily those that never experience difficult periods. They are often the ones that have created enough financial breathing room to deal with them.
That breathing room is your cash buffer.
A quiet month is not necessarily a bad month
One of the dangers of running a small business is treating every reduction in income as evidence that something has gone wrong.
Sometimes it has.
But not always.
Businesses can experience quieter periods because of:
- Seasonal demand.
- School holidays.
- Christmas.
- Customers delaying projects.
- Weather.
- Industry cycles.
- Clients taking holidays.
- A natural gap between contracts.
- The owner choosing to take some time away.
A quieter month does not automatically mean the business is failing.
The real problem arises when the business cannot financially tolerate normal fluctuations. If one slow week immediately creates difficulty paying bills, the problem may not be the quiet week itself.
It may be that there is no financial buffer between normal business activity and financial pressure.
What is a cash buffer?
A cash buffer is money deliberately kept available to help the business cope when income temporarily falls, or an unexpected cost appears.
Think of it as financial breathing space.
It is not money set aside for tax.
It is not money earmarked for a new van or laptop.
And ideally, it is not simply whatever happens to be left in the current account. It is a reserve with a specific purpose:
To give the business time.
- Time to wait for a late customer payment.
- Time to recover from a quiet month.
- Time to replace essential equipment.
- Time to make a sensible decision instead of an urgent one.
That last point is particularly important.
A cash buffer buys better decisions
Imagine two sole traders facing exactly the same problem.
A major customer postpones a £4,000 project by six weeks. The first business has almost no reserve. The second has enough cash set aside to cover several weeks of essential costs. The commercial problem is identical. But the decisions available to each owner differ greatly.
The first may feel forced to:
- Accept poorly priced work.
- Offer unnecessary discounts.
- Take on a customer they would normally avoid.
- Use the tax pot.
- Put costs onto a credit card.
- Delay paying a supplier.
- Cancel planned marketing.
- Work excessive hours.
- Take the first opportunity that produces cash.
The second owner still needs to respond.
But they have time to think.
They can ask:
- Is this temporary?
- Which costs can reasonably be delayed?
- Should I increase sales activity?
- Is there an overdue invoice I should chase?
- Is this a good time to approach previous customers?
- Do I need to change anything fundamentally?
That is why a cash reserve provides more than just financial security.
It gives you decision-making space.
And good decisions are much easier to make when panic is not sitting beside you.
Start by working out your quiet-month number
Before deciding how much cash you should keep in reserve, you need to understand how much the business actually needs.
Start with one question:
What is the minimum amount needed to keep the business and your household functioning for one month?
Not your ideal month.
Not the amount you would like to spend.
The minimum realistic amount.
Look first at the business.
You might need to cover:
- Insurance.
- Rent or workspace costs.
- Vehicle payments.
- Software.
- Telephone and internet.
- Essential suppliers.
- Loan or finance repayments.
- Bookkeeping and professional fees.
- Wages or subcontractors.
- Other unavoidable operating costs.
Then consider what you personally need to take from the business.
This might include enough for:
- Mortgage or rent.
- Food.
- Utilities.
- Transport.
- Insurance.
- Other essential household commitments.
Put those together.
That gives you a useful starting point.
An example
Suppose your essential monthly business costs are:
- £600 vehicle and fuel costs.
- £250 software, telephone and insurance.
- £350 professional and finance commitments.
- £300 other essential business expenses.
Total essential business cost:
£1,500
You also need minimum personal drawings of:
£2,000
Your quiet-month number is therefore around:
£3,500
That does not mean £3,500 covers every possible expense.
It means that, at a basic level, you understand how much cash is needed to get through one month without creating an immediate crisis.
Now that is valuable information.
Now ask the uncomfortable question
Once you know your number, ask:
If no customer paid me anything from today, how long could the business continue?
You are not predicting disaster.
You are testing resilience.
Perhaps you have £7,000 sitting in the business account.
That might initially look like two months of breathing room.
But remember what we discussed in “Your Bank Balance Is Not Your Profit.”
Some of that money may already have another job.
Perhaps:
- £2,000 is reserved for tax.
- £1,000 is needed for VAT.
- £1,500 will pay supplier invoices.
Your genuinely available reserve may therefore be only £2,500.
Against a £3,500 quiet-month number, you have less than one month of real breathing room.
That may be less comfortable than you expected.
But knowing is useful.
Don’t count the tax pot
This deserves its own section because it is an easy trap. You may have £5,000 sitting in a separate savings account for tax.
Technically, the money exists.
But it is already committed.
If you use it to survive a quiet month, you have not solved the problem.
You have moved it. The immediate cash-flow pressure disappears, but the tax problem now sits in the future waiting for you.
That is why it helps to distinguish clearly between:
Tax reserve
Money expected to be needed for taxes.
VAT reserve
Where applicable, money potentially due to HMRC.
Business reserve
Money available to protect the business from fluctuations and unexpected events.
Different jobs.
Different pots.
How large should your cash buffer be?
There is no perfect answer that applies to every business.
A sole trader working from home with low overheads may need far less than a business with:
- Employees.
- Premises.
- Large finance payments.
- Stock.
- Expensive equipment.
- Significant supplier commitments.
You will often hear suggestions such as keeping three or six months of costs in reserve.
That may be sensible for some businesses.
But for a sole trader starting from almost nothing, it can also feel hopelessly unrealistic.
If your quiet-month number is £4,000, being told you should immediately have £24,000 sitting in savings does not feel particularly helpful.
So start smaller.
Build the first week
Instead of beginning with six months, ask:
What would one week of breathing room cost?
If your minimum monthly requirement is £4,000, a rough one-week target might be around £1,000.
That feels much more achievable.
Reach £1,000.
Then aim for £2,000.
Then a full month.
Then consider whether two or three months would make sense for your business.
This changes the goal from:
“I need to somehow save £24,000.”
to:
“I need to build my next £500 of resilience.”
Small targets create progress.
Use the good months wisely
A strong trading month creates an opportunity. Unfortunately, it can also create lifestyle inflation.
The business earns more. So spending rises. You upgrade equipment. Take more drawings. Add another subscription. Commit to another monthly cost.
Then income falls back to normal, but the higher costs remain.
A healthier approach is to decide in advance what happens when the business has an unusually good month.
Perhaps surplus cash is divided between:
- Tax.
- Business reserve.
- Planned investment.
- Personal reward.
There is nothing wrong with enjoying the benefit of a successful month.
The important thing is not to spend every good month as though it represents the new normal.
Some of that success can be used to protect future you.
The feast-and-famine problem
Many sole traders recognise this pattern.
Month one
You are extremely busy delivering work.
Month two
You are still busy finishing jobs and invoicing customers.
Month three
Work becomes quieter because you had very little time to market while delivering the previous jobs.
Month four
You panic and focus heavily on sales.
Month five
New work arrives.
And the cycle begins again.
A cash buffer cannot fix the sales process.
But it can stop the quiet part of the cycle from becoming an emergency.
That gives you the space to keep marketing consistently rather than only when the bank balance forces you to.
Build holidays into the plan
Sole traders face a particular challenge.
When you stop working, income may also stop. Employees usually continue to receive their salary while on annual leave. A sole trader may take a week away and lose a week of billable activity.
That does not mean you should avoid taking holidays. It means holidays need planning.
Suppose your business normally generates £1,500 a week from your direct work. A two-week holiday might affect £3,000 of potential income. Meanwhile, your regular costs continue.
If holidays are predictable, they should not really be treated as emergencies.
You can prepare for them.
A simple approach is to spread the cost across the year. If you want four weeks away each year, build that reality into your financial target. Your business needs to generate enough during the weeks you work to support the weeks when you do not.
What happens if your biggest customer disappears?
This is another useful resilience test.
Look at your customer list. Which customer contributes the largest amount of income?
Now imagine they disappear tomorrow. Not because you have done anything wrong.
Perhaps they:
- Close.
- Change supplier.
- Bring the work in-house.
- Lose a contract.
- Experience their own financial difficulty.
- Are acquired by another company.
What would happen to your business?
If one customer represents 40%, 50% or 60% of your income, the risk is significant. You may have an excellent relationship with them. That does not remove the risk. A cash reserve gives you time to replace lost income.
But the longer-term solution may also involve reducing dependency by developing a broader customer base.
Late payments make buffers even more valuable
A profitable sale does not help cash flow until the customer pays.
We explored this in “Late Payments Shouldn’t Keep You Awake.”
Imagine you are expecting £6,000 from customers this month. The money is due. The work has been completed. The invoices are valid. But two customers pay late.
Suddenly only £3,500 arrives.
Your business has not necessarily become less profitable. But your available cash has changed dramatically.
A reserve allows you to deal with late payment as a credit-control issue rather than an immediate survival problem.
You still chase the money.
You still protect your rights.
But you are not forced to make every decision based on whether the payment arrives tomorrow morning.
Unexpected costs will eventually happen
Even a well-run business experiences surprises.
- A laptop fails.
- A van needs repairing.
- Equipment breaks.
- A customer disappears owing money.
- An insurance excess needs paying.
- A supplier suddenly requires payment upfront.
The question is not whether something unexpected will ever happen. It is how disruptive it will be when it does.
If every surprise requires debt, a credit card or money from the tax account, the business has very little financial shock absorption.
A reserve acts as that shock absorber.
Your reserve can stop you taking bad work
This is one of the least discussed benefits. When cash is desperately short, almost any paying job can look attractive.
You may accept:
- A customer who immediately gives you concerns.
- Work outside your normal expertise.
- An unrealistic deadline.
- A price you know is too low.
- Poor payment terms.
- A project you simply do not want.
You tell yourself:
“I need the money.”
Sometimes that may genuinely be true. But it puts the customer in a powerful position.
A cash reserve allows you to ask:
“Is this actually good business?”
That is a much better question.
Do not build the buffer with debt and call it savings
There is a difference between available borrowing and a cash reserve.
An overdraft or credit card may provide short-term emergency support.
But borrowed money:
- Has to be repaid.
- May carry interest.
- May be withdrawn or reduced.
- Creates another monthly commitment.
A £5,000 available credit limit is not the same as having £5,000 of your own cash reserved.
Credit can be useful.
But it should not create a false sense of security.
Create a separate reserve account
One of the simplest ways to build a buffer is to keep it away from everyday spending.
You could use:
- A separate business savings account.
- A dedicated banking pot or space.
- Another clearly identified reserve account.
Give it a name.
Business Buffer
Quiet Month Fund
Business Reserve
The label matters more than it might appear. Money without a job is easy to spend. Money labelled Business Reserve has a purpose.
Automate small amounts
You do not have to rely on finding a large lump sum.
Consider moving money regularly.
For example:
- £25 a week.
- £50 a week.
- £200 a month.
- 5% of customer receipts.
- A proportion of any income above your normal monthly target.
The right amount depends on the business. Consistency matters more than choosing the perfect figure on day one.
£50 a week becomes £2,600 over a year before considering any interest.
That may not create a six-month reserve.
But it might be enough to turn an equipment failure from a crisis into an inconvenience.
Review the buffer as the business grows
If your costs change, your reserve target should change too.
Perhaps the business originally needed £2,500 a month to operate.
Two years later you have:
- A larger vehicle payment.
- More software.
- An employee.
- Premises.
- Higher personal drawings.
Your minimum monthly requirement might now be £5,000.
A £5,000 buffer that once provided two months of breathing room now provides one.
Review your quiet-month number periodically.
Your reserve should reflect the business you have today, not the one you had three years ago.
What if you currently have no buffer at all?
Then begin from where you are. There is no benefit in feeling guilty about the money you did not save previously.
Look at the business today.
Ask:
- What is my minimum monthly requirement?
- How much genuinely uncommitted cash do I currently have?
- What would one week of reserve look like?
- What small regular amount could I start transferring?
- Is there unnecessary spending I could redirect?
- Could part of the next unusually strong month go into the reserve?
Your first target might be £250.
Then £500.
Then £1,000.
Financial resilience is built. It does not need to appear overnight.
A simple Quiet-Month Test
Set aside 20 minutes this week.
Step 1 — Calculate your essential business costs
What must be paid even if sales temporarily stop?
Step 2 — Add your minimum personal requirement
What do you genuinely need to draw to cover essential household costs?
Step 3 — Create your monthly survival number
Add the two figures together.
Step 4 — Identify genuinely available cash
Exclude money already reserved for:
- Tax.
- VAT.
- Supplier bills.
- Other committed spending.
Step 5 — Calculate your breathing room
If your monthly minimum is £4,000 and you have £2,000 genuinely available, you have roughly half a month of cover.
If you have £8,000, you have around two months.
The calculation does not have to be mathematically perfect.
The purpose is awareness.
Step 6 — Choose your first target
Do not automatically aim for six months.
Decide what would make the business meaningfully safer.
Perhaps:
- One week.
- Two weeks.
- One month.
Step 7 — Start the transfer
Put the first amount aside.
Even £25 changes the status from:
“I should build a reserve.”
to:
“I am building a reserve.”
That matters.
Where good bookkeeping fits in
Building a sensible cash buffer depends on understanding what the business actually costs.
If the records are not current, it becomes difficult to answer basic questions such as:
- What are our normal monthly overheads?
- How much do I usually draw?
- Which costs are essential?
- How much do customers still owe?
- What tax needs reserving?
- Are costs increasing?
- Is the business consistently profitable?
This is where bookkeeping becomes more than record-keeping.
Accurate, current information helps you understand the financial shape of the business.
At Zenith Bookkeeping, we believe that clarity makes financial decisions easier.
You cannot prevent every quiet month.
But you can prepare for one.
A final thought: resilience comes from breathing room
A quiet month should not automatically become a crisis.
Neither should:
- A late-paying customer.
- A broken laptop.
- A week off.
- A cancelled project.
- An unexpected repair.
These things happen.
The difference is whether the business has enough breathing room to respond calmly.
A cash buffer will not solve every problem. But it can buy something extremely valuable. Time.
- Time to think.
- Time to act.
- Time to replace income.
- Time to make a better decision.
And perhaps most importantly, time to avoid making a bad decision simply because the bank account forced your hand.
So my advice is to start small. Build gradually. Protect it.
Because the goal is not to create a business that never experiences difficult months.
It is to create one that can cope when they arrive.
Would a quiet month put your business under pressure?
If you are a sole trader or small-business owner in Norfolk and unsure how much your business genuinely needs each month, Zenith Bookkeeping can help.
Clear, accurate bookkeeping can help you understand your regular costs, what customers owe you, what needs to be reserved, and how much financial breathing room the business really has.
Zenith Bookkeeping provides straightforward bookkeeping support and practical financial organisation in plain English.
Start a conversation with Zenith Bookkeeping today and begin building a clearer, calmer and more financially resilient business.
This article provides general information and should not be treated as individual accounting, tax or financial advice. The appropriate level of cash reserves will depend on your business and personal circumstances. Obtain appropriately qualified advice where necessary.